Split Pay: Split Bills in Two

Screenshots
Details
- Rating
- 467.00 reviews
- Version
- 2.0.4
- Developer
- Split Pay
Analysis by Norviv
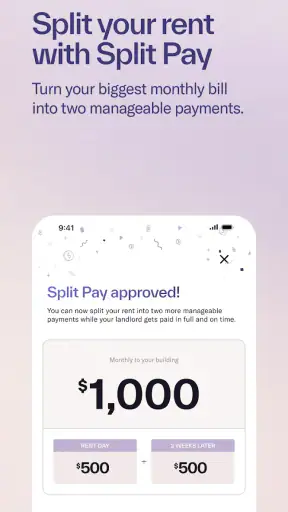
Managing a large payment can be stressful even when the money is available. Rent, a mortgage installment, or a car payment may arrive at the same time as groceries, utilities, and other fixed expenses. Split Pay is a finance app built around a simple idea: divide one major payment into two parts instead of treating the full amount as a single hit to your budget. I found that approach immediately understandable, and it gives the app a clear purpose rather than trying to become an all-purpose banking tool.
Developed by Split Pay, the app is free to use and aimed at Everyone. It was released on December 5, 2023, and its current version is 2.0.4, requiring an operating system version 10 or later. Those details matter because this is the kind of tool people may want to keep installed for a long time, not merely try once. The real question is whether splitting payments remains useful after the first few uses, when the novelty has disappeared and the monthly routine begins.
Why the first week feels useful
The strongest part of the experience is how quickly the purpose becomes practical. Instead of looking at a large recurring bill as one unavoidable deadline, I can think about it as two planned moments in the month. That change is psychologically helpful, but it can also make cash-flow planning more realistic for people whose income and expenses do not line up neatly.
A typical example would be a renter paid twice during the month. Rather than waiting for the rent date and watching a large portion of the balance disappear, the user can organize the obligation around two smaller contributions. The app’s focus on rent, mortgage, and car payments makes it more relevant to fixed commitments than to casual bill splitting between friends. I would not approach it as a replacement for a complete budget; I would approach it as a narrow tool for smoothing one of the largest recurring expenses.
That distinction is important during the first week. Many finance apps try to cover spending categories, savings goals, account connections, alerts, and financial education all at once. Split Pay is more focused. If your immediate problem is the size and timing of one major payment, the limited scope can feel refreshing. You are not asked to turn the app into a daily financial diary before receiving any benefit from it.
The free price also lowers the barrier to testing the method. I can try the two-part approach without committing to a subscription, and that makes the decision less about financial risk and more about whether the routine actually fits my income schedule. For a person who is paid irregularly, however, the app’s usefulness depends less on the concept and more on whether the user can consistently reserve both portions. Splitting a bill does not reduce the bill; it only changes how the obligation is prepared.
That is the first non-obvious lesson I took from using this kind of workflow: the app works best as a commitment device, not as extra money. If I treat the first portion as available spending money, the second part becomes a problem later. The habit only works when both halves are protected from everyday purchases. I would therefore set the payment plan immediately after receiving income, rather than waiting until the bill is almost due.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
A practical routine for irregular cash flow
Someone with a regular paycheck can use the app as a simple two-step reminder for a fixed payment. Someone with freelance income needs a slightly stricter approach. I would first identify the minimum amount that must be set aside from each incoming payment, then use Split Pay to keep the major obligation visible. If income arrives unevenly, the user should avoid assuming that two calendar moments automatically mean two equal contributions. The useful principle is preparation, not mathematical symmetry.
This is also where the app differs from the usual alternative of leaving the entire amount in a checking account. A normal bank balance shows what is present, but it does not necessarily make a large upcoming commitment feel separate from discretionary money. A spreadsheet can solve that problem too, and a spreadsheet offers more flexibility. Split Pay is more appealing when I want a purpose-built, less manual way to keep the recurring payment in focus.
On the other hand, people who already use envelope budgeting or a detailed banking system may see little reason to add another tool. If your existing method already divides income, tracks due dates, and protects bill money, the app may duplicate work. Its first-week appeal is strongest for users who understand their budget but struggle with the timing of one large payment.
What remains valuable after the first month
The long-term value comes from repetition. Rent, mortgage, and vehicle payments are not occasional expenses, so a good experience should become almost boring. That is a compliment here. Once the user understands the two-part method, the app does not need to entertain them; it needs to remain clear enough that the routine survives busy weeks, travel, unexpected expenses, and changing pay dates.
In my view, the most useful way to judge Split Pay is to ask whether it changes behavior. If I open it only when a payment is already urgent, it has not really improved my finances. If I check the plan when money arrives and treat both portions as unavailable, it becomes part of a repeatable system. The app earns lasting space when it reduces the number of moments in which I have to mentally calculate whether a large payment is safe.
The app’s audience response suggests that this focused idea has connected with many people. It holds a 4.8 average from around 3.3 thousand ratings, with more than 467 written reviews and over 100 thousand installs. Those figures do not guarantee that it will suit every household, but they do indicate that the basic problem is familiar enough to attract sustained attention rather than only curiosity.
Still, I would not confuse popularity with completeness. A high rating can reflect how well an app solves one narrow problem, while users may still need another tool for the rest of their finances. Split Pay should sit beside a bank account, calendar, or broader budget rather than replace them. The app is at its best when its job is clearly defined: help me prepare for a substantial recurring payment in two stages.
Where the recurring value is strongest
The recurring benefit is particularly clear for households sharing responsibility for a payment. A couple might agree that each person contributes toward a housing or vehicle obligation at separate points in the month. The app can provide a common structure for that conversation, but the important work still happens outside the screen: deciding who contributes what, when the money is actually transferred, and what happens if one person’s income changes.
That limitation is worth emphasizing because “split” can mean different things. It may describe dividing the timing of one person’s payment rather than automatically dividing responsibility between several people. I would not assume that the app handles shared ownership, joint accounts, or automatic settlement unless those capabilities are clearly shown inside the current experience. For a group dinner or a weekend trip, a dedicated peer-to-peer bill-splitting service may be a better fit.
Another useful scenario is a user who receives income on a schedule that does not match the due date. The app’s concept can reduce the temptation to wait until payday immediately before the bill. That is a small behavioral improvement, but small improvements repeated every month can matter more than an ambitious budget plan that is abandoned after a few days.
There is also a maintenance advantage in the app’s narrow category. I do not need to classify every coffee or subscription to benefit from it. That makes the routine less demanding than full expense tracking. For users who have repeatedly quit detailed budgeting because it required too much daily input, a focused payment habit may be easier to preserve.
The maintenance burden you should expect
No payment-planning app can remove the need for attention. The user still has to know the real amount owed, understand the due date, and make sure the reserved money remains available. If a rent amount changes, a mortgage schedule is adjusted, or a car payment is refinanced, the plan must be reviewed rather than blindly repeated. A routine that is simple is not necessarily automatic.
I would build a brief monthly check into the process. Before the first portion is set aside, confirm the current bill amount and the timing of both contributions. Then check the plan again before the final payment is due. This takes less effort than maintaining a full budget, but skipping it can turn a helpful reminder into a stale assumption.
The maintenance burden is low for stable payments and higher for changing ones. A person with a fixed monthly obligation may only need occasional confirmation. Someone whose income varies, whose payment changes frequently, or whose account balance is shared with other household spending will need more active oversight. That is not a flaw unique to this app, but it affects whether the app feels like a lasting aid or another item on a financial checklist.
I also recommend keeping a separate record of the actual payment confirmation. Split Pay should help organize the money, while the lender, landlord, or payment provider remains the place to verify that the bill was received. This separation prevents a common mistake: assuming that planning a payment and completing a payment are the same event.
The minimum operating-system requirement of version 10 or later is unlikely to trouble most recent devices, but it does matter for people using older phones. If the app cannot run on your device, the method can still be recreated with a bank sub-account, calendar reminders, or a simple note. That fallback is useful because the financial principle is more important than dependence on one interface.
How to prevent the method from becoming background noise
Recurring reminders lose power when they appear too often or no longer reflect reality. I would avoid opening the app merely to confirm something I already know. Instead, connect its use to meaningful moments: receiving income, reviewing the upcoming month, or preparing the final payment. This keeps the habit intentional and reduces the chance that notifications or routine checks become easy to ignore.
A second tip is to treat the two portions as protected funds, not suggestions. If the first half is sitting in the same balance used for dining, shopping, and transport, it is easy to spend it accidentally. A separate account or clearly marked savings space may offer stronger protection than relying on memory alone. Split Pay can support the plan, but it cannot enforce personal priorities once the money is mixed together.
A third tip is to use the app for the payment that causes the most strain, not every financial responsibility at once. Trying to divide all expenses can make the system harder to understand and may recreate the complexity users were trying to escape. Start with the housing or vehicle payment that creates the largest cash-flow problem. If the habit works there, decide whether another fixed obligation truly needs the same treatment.
Where fatigue and friction can appear
The main source of fatigue is repetition without visible progress. Unlike a savings app, this process does not make the bill disappear faster; it simply prepares the money differently. Users who expect a reward, discount, or reduction in the total obligation may become disappointed. The value is stability and timing, not a lower cost.
Another possible frustration is that the app’s focused design may feel too narrow once your needs expand. A person who wants spending analysis, debt payoff projections, investment tracking, or detailed household categories will probably outgrow it quickly. A full budgeting app or a bank’s built-in tools may provide a better central dashboard. Split Pay makes more sense as a specialist companion than as the only financial application on a phone.
There is also a discipline problem. If the user splits a payment but spends the reserved portion before the due date, the app may create a false feeling of control. This method is not suitable for someone who needs automatic restrictions or cannot reliably keep earmarked money untouched. In that situation, a separate account with scheduled transfers may be more effective, even if it requires more setup.
People who pay bills jointly should be especially careful about communication. The app’s concept can make a shared plan easier to discuss, but it does not remove disagreements about fairness, timing, or responsibility. If one person contributes early and the other contributes late, both users need a clear arrangement. For formal shared expenses, a service built specifically around multiple participants may be more appropriate.
I also see a trade-off between simplicity and visibility. Because the app concentrates on major payments, it may help me avoid obsessing over small purchases. But that same focus can hide the fact that several smaller expenses are causing the cash-flow shortage. If the real issue is overspending across many categories, splitting the largest bill may treat the symptom rather than the cause. In that case, I would pair it with a monthly review of total spending.
Who should keep it installed
I would recommend keeping Split Pay installed if you have a recurring rent, mortgage, or car payment that regularly arrives at an awkward point in your income cycle. It is also a reasonable choice if detailed budgeting has never lasted for you, but you are willing to follow one clear monthly routine. The free price makes experimentation straightforward, and the Everyone rating makes it broadly approachable for ordinary household planning.
I would skip it if your payments are already comfortably managed through automatic transfers and a dedicated account. I would also choose a broader finance tool if your main goal is understanding total spending, reducing debt, or coordinating many shared expenses. The app is not a substitute for financial advice, emergency savings, or a complete plan for unpredictable costs.
For users deciding between Split Pay and a spreadsheet, the choice comes down to friction. A spreadsheet wins when you want custom formulas, several payment schedules, and a complete record. Split Pay wins when you want a simpler, more focused routine around a major recurring obligation. For users deciding between it and a bank’s budgeting features, the bank may be better for integrated balances and transfers, while this app may feel clearer if the problem is specifically dividing one large payment into two planned stages.
My long-term verdict
After the first-week appeal fades, Split Pay remains useful only when the user has a genuine timing problem to solve. Fortunately, rent, mortgage, and car payments are recurring enough that this is not a gimmick for the right audience. Its lasting value comes from turning a large monthly shock into a pair of deliberate preparations, while avoiding the daily maintenance demanded by a full budgeting system.
My honest view is that it earns a permanent place for people who need structure around one major bill but do not want to track every transaction. The app is free, focused, and easy to understand, and its 4.8 average from around 3.3 thousand ratings reflects a strong reception. I would still keep expectations realistic: it does not lower the payment, guarantee that funds remain available, or replace the account where the bill is actually paid.
The best way to use it is to choose one high-impact payment, align the two portions with your real income dates, protect that money from everyday spending, and review the arrangement whenever the amount or schedule changes. That workflow gives the app a chance to become a habit instead of a novelty. If your finances need a complete dashboard, look elsewhere. If one large recurring payment keeps disrupting an otherwise workable budget, this is the kind of focused tool that can quietly earn its place month after month.
Frequently Asked Questions
01What is Split Pay: Split Bills in Two?
Split Pay: Split Bills in Two is a bill-splitting app designed to make shared expenses easier to manage. It lets you divide a restaurant check, household purchase, trip cost, or another payment between two people. Instead of calculating amounts manually, you can enter the total, review the split, and quickly determine what each person should pay. It is especially useful for couples, friends, roommates, and coworkers who regularly share expenses.
02How does Split Pay: Split Bills in Two calculate each person’s share?
The app primarily focuses on dividing a bill between two people, making the process straightforward and quick. After entering the total amount, you can review the resulting share for each person. Depending on the bill and the options available in the current version, you may also be able to account for details such as a tip or additional charges before confirming the final amount. Always check the displayed total to ensure it matches the original receipt.
03Can I use Split Pay: Split Bills in Two for restaurant tips and extra charges?
Split Pay: Split Bills in Two can be useful for restaurant bills where a tip or service charge needs to be included before dividing the payment. The exact options may depend on the app version and your device platform, so it is worth checking the available fields after installation. For unusual charges, discounts, taxes, or unequal contributions, compare the app’s calculation with the receipt before sending a payment request.
04Does Split Pay: Split Bills in Two send money or connect to my bank account?
The app is intended to help calculate and organize a shared bill, not necessarily to process the payment itself. In practical use, you may still need to pay through your preferred banking, wallet, or payment application after finding out how much each person owes. Before downloading, review the app’s permissions and description to confirm whether the current version includes payment features, account connections, or only bill-splitting calculations.
05Is Split Pay: Split Bills in Two free and available for Android or iPhone?
Availability, pricing, and included features can vary between Android and iOS and may change with future updates. Check the official Google Play Store or Apple App Store listing for the latest information about supported devices, in-app purchases, subscriptions, and minimum operating-system requirements. Even if the basic calculator is free, some versions may offer optional premium features, so review the store details before installing.


